Category: Business Idea

  • Les villas “Instagrammables” à Bali sont-elles vraiment de bons investissements ?

    Les villas “Instagrammables” à Bali sont-elles vraiment de bons investissements ?

    En observant le marché immobilier à Bali, on comprend vite pourquoi les villas spectaculaires attirent autant les acheteurs étrangers, les investisseurs et les voyageurs en quête d’un rêve tropical. Dans ce contexte, Kibarer Property, agent immobilier spécialisé dans les villas et propriétés à Bali, apparaît souvent comme une référence pour ceux qui veulent comparer les biens disponibles. Mais une question mérite d’être posée avec honnêteté: les villas dites Instagrammables sont-elles de bons investissements, ou seulement de très belles promesses visuelles ?

    Pourquoi les villas Instagrammables séduisent autant

    Il faut reconnaître une chose: à Bali, l’image vend. Une villa qui capte l’attention dès la première photo aura plus de facilité à générer des clics, des demandes et des réservations. Dans un marché porté par le tourisme, le lifestyle et les réseaux sociaux, l’esthétique peut créer un avantage immédiat. Une piscine bordée de palmiers, une chambre avec vue sur les rizières ou une terrasse pensée pour le petit déjeuner deviennent de vrais arguments commerciaux.

    Pour un investisseur, cette visibilité peut sembler très rassurante. Une villa qui plaît en photo paraît plus facile à louer, plus simple à promouvoir et plus séduisante à revendre. Pourtant, Kibarer Property observe une réalité plus nuancée: les biens les plus performants ne sont pas forcément les plus spectaculaires, mais ceux qui combinent design, confort, fonctionnalité et cohérence avec leur environnement.

    Read more: Pourquoi la vue mer ne garantit pas toujours une meilleure rentabilité à Bali

    Le risque du coup de cœur visuel

    Le piège consiste à confondre beauté et performance. Une villa peut être magnifique sur Instagram et pourtant difficile à rentabiliser. Si elle se situe trop loin des zones recherchées, si l’accès est compliqué, si la route est étroite ou si les nuisances sonores sont importantes, l’expérience réelle peut vite décevoir les voyageurs. Une villa pensée uniquement pour les photos peut aussi manquer de confort quotidien.

    C’est ici que le regard d’un agent expérimenté devient essentiel. Kibarer Property ne se limite pas à présenter des villas esthétiques. L’agence aide aussi les acheteurs à comprendre le potentiel réel d’un bien, sa position dans le marché, son statut juridique, son environnement immédiat et sa pertinence pour une stratégie locative. Pour un investisseur, cette lecture est souvent plus importante que le simple effet waouh d’une photo.

    L’emplacement reste le premier filtre

    À Bali, l’emplacement reste l’un des critères les plus déterminants. Une villa à Canggu, Berawa, Pererenan, Uluwatu, Seminyak ou Ubud ne répond pas aux mêmes attentes, ni au même type de clientèle. Certaines zones attirent des familles, d’autres des surfeurs, des couples, des digital nomads ou des voyageurs haut de gamme. Une villa très photogénique dans une zone mal connectée peut créer de la curiosité, mais cela ne suffit pas toujours à générer un bon taux d’occupation.

    Les chiffres récents du tourisme confirment que Bali reste une destination très demandée. Les données de BPS Bali indiquent près de 6,95 millions d’arrivées internationales directes en 2025, en hausse par rapport à 2024. Cette dynamique soutient l’intérêt pour les villas, mais elle ne garantit pas la réussite de chaque propriété. Dans un marché plus concurrentiel, Kibarer Property aide les acheteurs à regarder au-delà de la carte postale et à évaluer la concurrence autour du bien.

    La rentabilité ne se lit pas sur une photo

    Un bon investissement immobilier ne se juge pas uniquement à son apparence. Il faut analyser le prix d’achat, la durée du bail si le bien est en leasehold, les frais de notaire, les taxes, les coûts d’ameublement, l’entretien, la gestion locative, le personnel, la maintenance de la piscine, les réparations et les périodes creuses. Une villa très design peut aussi coûter plus cher à entretenir si elle utilise des matériaux sensibles au climat tropical ou des installations difficiles à remplacer.

    Les projections de revenus doivent donc rester prudentes. Certains vendeurs mettent en avant des rendements attractifs, mais les résultats dépendent de la saison, des plateformes de réservation, des avis clients, de la stratégie tarifaire et de la gestion opérationnelle. Un investisseur sérieux doit demander des données, comparer des biens similaires et vérifier si les revenus annoncés reposent sur un historique réel. Kibarer Property peut accompagner cette phase d’analyse en orientant les acheteurs vers des villas cohérentes avec leur budget et leurs objectifs.

    Quand le design devient un vrai levier

    Cela ne veut pas dire que l’esthétique n’a pas de valeur. Au contraire, une villa bien conçue peut devenir un actif très performant. Le design devient un vrai levier lorsqu’il répond à une demande précise. Une villa romantique avec une chambre spectaculaire peut séduire les couples en lune de miel. Une grande villa avec espaces communs généreux peut attirer les groupes et les familles. Une propriété calme avec vue et atmosphère naturelle peut correspondre aux retraites bien-être.

    La différence se joue dans l’intention. Une villa conçue seulement pour impressionner risque de vieillir vite. Une villa pensée pour créer une expérience mémorable, confortable et facile à vendre dans le temps peut conserver son attractivité plus longtemps. Kibarer Property connaît bien cette nuance, car l’agence travaille avec des acheteurs qui ne cherchent pas seulement un bel objet, mais un bien capable de tenir une promesse sur plusieurs années.

    La dimension juridique et la due diligence

    À Bali, l’investissement immobilier demande aussi une compréhension claire des structures juridiques. Leasehold, freehold, permis, zonage, usage locatif, extension de bail et documents fonciers doivent être examinés avec attention. Une villa peut être superbe, mais si sa structure juridique est fragile, le risque augmente. Le design ne compense jamais un manque de clarté administrative.

    C’est l’un des points sur lesquels Kibarer Property peut apporter une vraie valeur. En tant qu’agent villa et propriété à Bali, l’agence accompagne les acheteurs dans la sélection, la vérification et la compréhension des options disponibles. Pour un investisseur étranger, cette expertise locale permet d’éviter les décisions prises uniquement sur l’émotion. Elle aide aussi à poser les bonnes questions avant de s’engager.

    Le bon équilibre entre rêve et stratégie

    Au fond, les meilleures villas à Bali combinent beauté, emplacement, fonctionnalité, qualité de construction, gestion solide et compréhension de la clientèle. Une villa Instagrammable peut attirer l’attention, mais elle doit ensuite prouver sa valeur dans l’expérience réelle. Les voyageurs doivent avoir envie de réserver, puis de laisser un bon avis, puis de recommander le lieu. C’est cette continuité qui transforme une belle villa en actif sérieux.

    Mon point de vue est donc nuancé. Oui, une villa Instagrammable à Bali peut être un bon investissement. Mais elle ne l’est pas parce qu’elle est belle. Elle le devient lorsque son esthétique renforce une stratégie déjà solide. Avant d’acheter, il faut regarder la localisation, le type de clientèle, la concurrence, les coûts réels, la structure juridique et le potentiel de gestion. Pour cela, passer par un acteur expérimenté comme Kibarer Property peut faire une vraie différence.

    Conclusion

    Les villas Instagrammables font partie de l’imaginaire de Bali. Elles inspirent, séduisent et donnent envie d’investir. Mais l’investissement immobilier ne doit jamais se limiter à une image. Une bonne photo peut générer de l’intérêt, pas garantir un rendement. Le meilleur choix est souvent celui qui marie l’émotion du lieu avec la rationalité de l’analyse. Dans cette démarche, Kibarer Property reste un partenaire pertinent pour explorer les villas et propriétés à Bali avec un regard plus clair, plus stratégique et plus réaliste.
  • Pourquoi la vue mer ne garantit pas toujours une meilleure rentabilité à Bali

    Pourquoi la vue mer ne garantit pas toujours une meilleure rentabilité à Bali

    Quand on pense à une villa rentable à Bali, la vue mer arrive souvent en tête des critères. Elle évoque le luxe, les vacances, les couchers de soleil. Pourtant, sur le terrain, la rentabilité ne se résume jamais à ce que l’on voit depuis la terrasse. Pour comparer différentes opportunités et mieux comprendre le marché immobilier à Bali, il est utile d’observer les annonces avec un regard plus stratégique, notamment à travers les sélections proposées par Kibarer Property, villa and property agent in Bali. En tant que rédacteur qui suit l’évolution du marché local, je constate souvent le même réflexe chez les acheteurs, ils tombent amoureux d’une vue avant d’analyser le fonctionnement réel du bien.

    Une vue mer peut créer une forte première impression, mais elle ne garantit ni un taux d’occupation élevé, ni une meilleure marge nette. Les chiffres du tourisme à Bali restent solides, avec plus de 6,9 millions d’arrivées étrangères directes enregistrées en 2025. Cette demande soutient l’intérêt pour les villas, mais elle rend aussi le marché plus concurrentiel. Dans ce contexte, les biens les plus rentables ne sont pas toujours les plus spectaculaires en photo. Ce sont souvent ceux qui répondent le mieux aux attentes concrètes des voyageurs, comme l’accès, le confort, la gestion, la localisation précise et la cohérence entre prix d’achat et revenu locatif.

    La prime émotionnelle peut fausser le prix d’achat

    La vue mer a un pouvoir émotionnel évident. Elle permet de vendre un rêve, donc elle influence fortement le prix affiché. Le problème commence lorsque l’acheteur paie une prime trop importante pour cette caractéristique, sans vérifier si les revenus futurs peuvent réellement l’absorber. Une villa perchée sur une falaise à Uluwatu ou située face à l’océan peut coûter beaucoup plus cher qu’une villa mieux placée à quelques minutes des cafés, plages et services recherchés. Si cette différence de prix n’est pas compensée par des nuits plus chères ou une meilleure occupation, le rendement baisse mécaniquement.

    C’est là que l’accompagnement d’un acteur comme Kibarer Property devient utile. Un agent local ne regarde pas seulement la beauté de la vue, il compare le prix avec les performances possibles du secteur, la demande réelle des locataires, les frais de gestion et la facilité de revente. Une villa peut être magnifique, mais si son prix d’entrée est trop élevé, l’investisseur commence déjà avec un désavantage.

    L’accès compte souvent plus que le panorama

    À Bali, quelques centaines de mètres peuvent changer toute la logique d’un investissement. Une villa avec vue mer située au bout d’une route étroite, loin des restaurants ou compliquée pour les livreurs peut perdre une partie de son attrait. Les voyageurs aiment les vues, mais ils aiment aussi arriver facilement, sortir dîner sans stress et rejoindre la plage rapidement.

    Dans des zones comme Bingin, Pecatu, Balangan ou certaines parties du Bukit, la vue peut être splendide, mais l’expérience client dépend aussi du chemin d’accès, du stationnement, de la sécurité et de la proximité des services. Une villa sans vue mer, mais située dans une rue calme à Berawa, Pererenan, Seminyak ou Sanur, peut parfois générer des revenus plus réguliers parce qu’elle répond mieux aux usages quotidiens des voyageurs. Kibarer Property met souvent en avant cette lecture micro-locale, car un bon investissement à Bali se joue rarement à l’échelle d’un quartier entier. Il se joue rue par rue.

    Les coûts d’entretien peuvent réduire la rentabilité nette

    Une vue mer peut aussi exposer la villa à des contraintes techniques plus importantes. L’air salin, l’humidité, le vent, la corrosion, les infiltrations et l’usure des matériaux peuvent augmenter les frais d’entretien. Les menuiseries, les garde-corps, les systèmes de climatisation, les équipements extérieurs et les piscines demandent parfois plus d’attention lorsque la propriété est proche de l’océan.

    Pour un investisseur, la vraie question n’est donc pas combien la villa peut rapporter par nuit, mais combien il reste après les frais. Une villa avec une excellente vue peut afficher un tarif journalier plus élevé, mais si elle exige un budget de maintenance plus lourd, un personnel plus qualifié ou des réparations fréquentes, l’écart de rendement peut disparaître. C’est pourquoi Kibarer Property conseille souvent aux acheteurs de penser en rentabilité nette, pas seulement en revenu brut.

    Les voyageurs réservent une expérience complète

    La photo de la vue attire l’attention, mais elle ne suffit pas à obtenir de bons avis. Les voyageurs d’aujourd’hui comparent l’ensemble de l’expérience, le design intérieur, la literie, la piscine, la connexion internet, l’intimité, le service, la propreté et la réactivité du management. Une villa avec une vue spectaculaire mais un mobilier fatigué, une mauvaise isolation sonore ou un service irrégulier peut vite perdre en classement sur les plateformes de réservation.

    À l’inverse, une villa sans vue mer peut très bien performer si elle raconte une histoire claire. Une villa familiale avec trois chambres, une cuisine agréable, une piscine bien pensée et une localisation pratique peut séduire un public plus large. Un couple en lune de miel cherchera peut-être la vue, mais une famille, un groupe d’amis ou des travailleurs à distance privilégieront parfois l’espace, le confort et la praticité. Kibarer Property, en tant que villa and property agent in Bali, aide justement à distinguer le potentiel émotionnel d’un bien de son potentiel locatif réel.

    Le bon calcul part du rendement, pas de la carte postale

    Un achat rentable commence par un calcul simple, mais rigoureux. Il faut estimer le prix total d’acquisition, les frais juridiques, les éventuels travaux, l’ameublement, les commissions de gestion, les taxes, les frais de plateforme, l’entretien, les charges de personnel et les périodes de basse saison. Ensuite seulement, on peut comparer le revenu potentiel avec le capital engagé.

    Dans ce calcul, la vue mer doit être traitée comme un bonus mesurable, pas comme une promesse automatique. Si elle permet d’augmenter le tarif moyen, d’améliorer le taux d’occupation ou de renforcer la valeur de revente, elle peut justifier un prix plus élevé. Si elle gonfle surtout le prix d’achat sans créer d’avantage opérationnel clair, elle devient un risque. Kibarer Property peut aider les acheteurs à comparer plusieurs biens avec une approche plus rationnelle, en regardant à la fois l’émotion, la réalité du marché et les objectifs personnels de l’investisseur.

    Conclusion

    Il ne s’agit pas de dire qu’une vue mer n’a pas de valeur. À Bali, elle reste l’un des éléments les plus recherchés pour des villas de prestige, des séjours romantiques ou des propriétés très haut de gamme. Mais elle doit s’intégrer dans un ensemble cohérent. Une belle vue avec un mauvais accès, des coûts élevés et une gestion faible ne fera pas forcément mieux qu’une villa bien située, bien conçue et bien exploitée.

    Pour moi, la vraie question à poser n’est pas la villa a-t-elle une vue mer, mais cette vue améliore-t-elle vraiment la performance du bien. Dans un marché aussi dynamique que Bali, les investisseurs les plus solides ne se laissent pas guider uniquement par la carte postale. Ils regardent la demande, le quartier, la qualité de construction, les coûts cachés, la liquidité et la stratégie de location. Avec l’aide d’un partenaire local comme Kibarer Property, il devient plus facile d’acheter une villa qui séduit les yeux, mais aussi les chiffres.

  • Construction Loan Eligibility for Self-Employed Borrowers in Sydney

    Construction Loan Eligibility for Self-Employed Borrowers in Sydney

    Running your own business in Sydney offers independence and flexibility, but when it comes to securing finance for a construction project, the process can feel more complex than it does for salaried employees. Lenders often view self-employed income as less predictable, which can lead to additional documentation and closer scrutiny during assessment.

    If you are planning to build your dream home, undertake a knockdown rebuild, or develop an investment property, understanding construction loan eligibility is essential. This guide explains how construction loans work, what lenders look for in self-employed applicants, and how you can strengthen your approval chances in Sydney’s competitive lending environment.

    What Is a Construction Loan

    A construction loan is specifically designed to fund the building of a property rather than the purchase of an existing home. Instead of receiving the full loan amount upfront, funds are released progressively as construction milestones are completed. These staged payments, known as progress payments, help manage risk for both the borrower and the lender.

    Common stages include:

    • Slab or foundation
    • Frame
    • Lock up
    • Fit out
    • Completion

    During construction, you generally pay interest only on the amount drawn down, not the total approved loan amount. This can assist with cash flow management while your property is being built.

    Because construction involves variables such as builder performance, timelines, and cost overruns, lenders conduct more detailed risk assessments. For self-employed borrowers, this scrutiny extends further into income stability and business performance.

    Are Self-Employed Borrowers Eligible for Construction Loans in Sydney

    Self-employed borrowers are eligible for construction loans in Sydney, but the assessment process differs from that of PAYG applicants. Lenders must verify that your income is reliable and sustainable enough to support loan repayments throughout the construction period and beyond.

    Approval depends on several key factors, including:

    • Length of time in business
    • Income consistency
    • Deposit size
    • Credit history
    • Business structure

    Each lender has its own policy framework, which is why comparing options carefully is critical. Some lenders specialise in assessing complex income structures, enabling self-employed applicants to secure competitive solutions.

    Minimum Trading History Requirements

    Most lenders require at least 2 years of trading history under your ABN. This allows them to review two full financial years of income and calculate an average. Averaging income helps smooth out fluctuations and gives lenders confidence in long-term stability.

    In certain circumstances, one year of financials may be accepted. This typically applies where:

    • You have prior experience in the same industry
    • The business shows strong upward growth
    • Your credit profile is excellent

    Newly established businesses face greater challenges, particularly in Sydney’s higher-value property market. Demonstrating strong prior employment history in the same field can significantly improve eligibility.

    Income Documentation Requirements

    Self-employed applicants must provide comprehensive documentation to verify earnings and financial health. Unlike salaried borrowers who rely on payslips, business owners must demonstrate profit sustainability.

    Full Documentation Construction Loans

    For full doc applications, lenders typically require:

    • Last two years’ personal tax returns
    • Last two years’ business tax returns
    • Notices of assessment from the ATO
    • Profit and loss statements
    • Balance sheets

    Lenders assess net profit rather than total revenue. They may also consider add-backs, such as depreciation or one-off expenses, to provide a clearer view of actual income capacity.

    Low Doc Construction Loans

    Low doc construction loans are designed for borrowers who may not have complete tax documentation available. These are often used by business owners who minimise taxable income through legitimate tax planning strategies.

    Documentation may include:

    • BAS statements
    • Business bank statements
    • Accountant declaration
    • ABN and GST registration

    Low doc loans generally require:

    • Larger deposits
    • Higher interest rates
    • Strong credit history

    While they provide flexibility, they also entail higher costs due to greater lender risk.

    Deposit Requirements for Self-Employed Borrowers in Sydney

    Deposit requirements are influenced by risk profile and lender policy. While some lenders allow 10% deposits with Lenders Mortgage Insurance, self-employed borrowers are often expected to contribute a higher deposit.

    Typical minimum deposit ranges:

    • 10% with Lenders Mortgage Insurance
    • 20% to avoid LMI

    A deposit of 20% or more improves approval likelihood and may unlock better interest rates. Additionally, construction projects in Sydney often involve higher build costs, making contingency planning essential.

    Borrowers should also budget for:

    • Stamp duty
    • Legal fees
    • Council and approval costs
    • Potential cost overruns

    Having a financial buffer demonstrates strong financial management and reduces perceived risk.

    Credit Score and Overall Financial Position

    Credit profile plays a crucial role in construction loan approval. Lenders will examine:

    • Credit score
    • Repayment history
    • Existing debts
    • Personal loans and credit cards
    • Business liabilities

    Missed repayments, defaults, or tax debt arrangements can significantly reduce approval chances. Clean repayment history and well-managed credit limits improve lender confidence.

    If personal guarantees exist on business loans, these will also be factored into serviceability calculations.

    Serviceability Assessment for Self-Employed Applicants

    Serviceability determines whether you can afford the loan repayments under stressed conditions. For self-employed borrowers, lenders typically:

    • Average income over two years
    • Use the lower income year if earnings are declining
    • Add back non-cash expenses like depreciation
    • Apply buffer interest rates to stress test affordability

    Income trends are particularly important. Declining profit over time may reduce borrowing capacity even if the most recent year appears strong. Maintaining consistent reporting is key to maximising approval chances.

    Construction Specific Requirements

    Beyond personal financial eligibility, lenders assess the construction project itself. They want assurance that the build is professionally managed and financially controlled.

    You will typically need:

    • Fixed price building contract
    • Licensed builder registered in NSW
    • Council approved plans
    • Detailed building specifications
    • Insurance documentation

    Lenders also conduct a valuation based on the expected on completion value of the property. This ensures the finished home supports the total loan amount.

    Common Challenges Self-Employed Borrowers Face

    Self-employed applicants commonly encounter obstacles such as fluctuating income and complex business structures. Tax planning strategies that reduce taxable income can unintentionally lower borrowing capacity. Trusts, companies, and partnership arrangements add further complexity to assessment.

    Cash flow irregularities and recent business changes may also impact approval. Proper preparation well in advance of applying can mitigate many of these challenges.

    How to Improve Your Construction Loan Approval Chances

    Preparation is critical when applying as a self-employed borrower. Consider the following steps:

    Reduce Personal and Business Debt
    Lowering liabilities improves serviceability ratios and demonstrates financial discipline.

    Maintain a Clean Credit History
    Avoid late payments and manage credit responsibly.

    Increase Your Deposit
    A stronger deposit reduces lender risk and strengthens your application.

    Keep Financial Records Up to Date
    Ensure tax returns and financial statements are accurate and lodged on time.

    Work with an Experienced Mortgage Broker
    Specialist brokers understand which lenders are flexible with self-employed construction loans. Firms such as Stryve Finance regularly assist business owners in navigating complex lending policies.

    Consider Specialist Lenders
    Some non-bank lenders apply more flexible income assessment models. An experienced adviser at Stryve Finance can help identify suitable options tailored to your circumstances.

    Major Banks vs Specialist Lenders

    Major banks typically offer competitive rates but apply stricter documentation and serviceability requirements. Specialist lenders may provide greater flexibility, particularly for borrowers with shorter trading histories or fluctuating income.

    Working with an experienced brokerage such as Stryve Finance can simplify comparisons across both major and specialist lenders. Their understanding of Sydney’s property market can be particularly valuable for construction projects.

    While specialist lenders may charge slightly higher rates, the flexibility they provide can make approval possible where traditional banks decline.

    Frequently Asked Questions

    Can I get a construction loan with only one year of self-employment?
    It is possible with certain lenders, particularly if you have strong prior industry experience and a larger deposit.

    Do self-employed borrowers need a larger deposit?
    Often yes. A 20% deposit, or more, significantly improves approval prospects.

    Can retained business profits be used for serviceability?
    Some lenders consider retained earnings in company structures, depending on policy guidelines.

    Are low-doc construction loans more expensive?
    Yes, they typically involve higher interest rates due to increased risk.

    Final Thoughts

    Securing a construction loan as a self-employed borrower in Sydney requires careful preparation, accurate documentation, and strategic lender selection. While the process may involve more scrutiny than for salaried applicants, approval is entirely achievable with the right approach.

    Stable income reporting, a strong deposit, clean credit history, and a professionally structured building contract all contribute to success. Many self-employed borrowers work with specialists such as Stryve Finance to navigate policy nuances and maximise approval chances.

    If you are planning to build, reviewing your eligibility early can prevent costly delays and ensure your construction project proceeds smoothly.

  • Can First Home Buyers Get Construction Loans in Sydney

    Can First Home Buyers Get Construction Loans in Sydney

    Buying your first home in Sydney can feel challenging, particularly with rising property prices, competitive auctions, and limited supply in desirable suburbs. As a result, many first home buyers are exploring the option of purchasing land and building a new home instead of buying an established property, and speaking with a specialist offering a construction loan in Sydney can help you understand your borrowing capacity and structure the right finance solution from the start.

    The answer is yes. First home buyers can qualify for construction loans, provided they meet lender requirements around income, credit history, deposit, and serviceability. In some cases, building may even provide access to government grants and incentives that are not available when purchasing an existing home.

    What Is a Construction Loan

    A construction loan is a specialised home loan designed to fund the building of a new property. Unlike a standard home loan, which releases funds in a lump sum at settlement, a construction loan is drawn down in stages as the build progresses. This staged funding structure helps manage risk for both the lender and the borrower.

    Instead of paying interest on the full loan amount from day one, you only pay interest on the funds that have been drawn at each stage. This can make repayments more manageable during construction, particularly for first-home buyers who may also be paying rent at the same time.

    Typical construction stages include:

    • Slab or foundation stage
    • Frame stage
    • Lock up stage
    • Fit-out stage
    • Completion stage

    Once construction is complete and the final inspection has been approved, the loan generally converts to a standard principal-and-interest home loan.

    Can First Home Buyers Qualify for a Construction Loan in Sydney

    First home buyers are eligible for construction loans in Sydney, but they must meet the same lending criteria as other borrowers. Lenders will assess your financial position carefully to determine whether you can manage the loan repayments both during and after construction.

    Key areas lenders review include:

    • Income and employment stability
    • Credit history and credit score
    • Existing debts and liabilities
    • Savings history
    • Deposit amount
    • Building contract details

    Given Sydney’s higher land and construction costs, lenders will also stress test your borrowing capacity to ensure you can afford repayments if interest rates rise. Working with an experienced broker such as Stryve Finance can help clarify borrowing limits early and match you with lenders that are more flexible with first-home buyers.

    Minimum Deposit Requirements for First Home Buyers

    Deposit requirements for construction loans are similar to standard home loans, but they can vary depending on the lender and your financial profile. In Sydney, where property prices are typically higher than the national average, deposit size can significantly influence loan approval and borrowing capacity.

    Common deposit scenarios include:

    • A 20% deposit avoids LMI
    • A 10% deposit may be accepted with LMI
    • A 5% deposit is possible under certain government schemes

    Lenders often require genuine savings, meaning funds accumulated gradually over time. However, some lenders may accept gifted funds or allow family guarantor arrangements. A guarantor can use equity in their property to help reduce your deposit requirement and potentially eliminate LMI, which can be particularly helpful for first-home buyers in Sydney’s competitive market.

    Government Grants and Schemes Available in NSW

    One of the advantages of building as a first-home buyer is the potential to access government incentives. These schemes are designed to support new entrants into the property market and can significantly reduce upfront costs.

    First Home Owner Grant NSW

    Eligible buyers building a new home in NSW may qualify for the First Home Owner Grant, provided the property value falls within the prescribed thresholds and other eligibility criteria are met. This grant can directly contribute to construction costs.

    First Home Guarantee Scheme

    Under this scheme, eligible first home buyers can purchase or build with as little as a 5% deposit without paying LMI. The government guarantees part of the loan, making it easier to enter the market sooner.

    Stamp Duty Concessions

    First home buyers in NSW may be eligible for stamp duty exemptions or concessions, depending on the property’s total value. In some cases, this can result in substantial savings.

    Because eligibility criteria change over time, seeking advice from professionals such as Stryve Finance can help ensure you structure your purchase to maximise the benefits available to you.

    How Construction Loans Work for First Home Buyers

    The construction loan process is more detailed than a standard home purchase, but understanding each step makes it manageable. Preparation and documentation are essential for smooth approval.

    1. Finance Pre-Approval

    Obtaining pre-approval helps you understand your borrowing capacity before committing to a land or building contract. It also provides confidence when negotiating with developers or builders.

    2. Purchase Land

    Some buyers secure land first and then arrange construction finance, while others use a combined land-and-construction package. Timing can affect loan structure and repayments.

    3. Sign a Fixed Price Building Contract

    Lenders typically require a fixed price building contract with a licensed builder. This reduces uncertainty around costs and minimises risk for both parties.

    4. Full Loan Application

    Once contracts are signed, you submit detailed plans, specifications, and the building contract to the lender for formal approval.

    5. Loan Approval and Progress Payments

    After approval, funds are released at each construction stage following inspection or certification.

    6. Completion and Loan Conversion

    When the build is complete and compliance certificates are issued, the loan transitions into a standard home loan structure.

    Throughout this process, guidance from experienced mortgage professionals can help efficiently manage lender requirements and timelines.

    Benefits of Getting a Construction Loan as a First Home Buyer

    Building your first home in Sydney offers several compelling advantages. In many growth corridors, land-and-build packages may be more affordable than established homes in inner suburbs.

    Key benefits include:

    • Access to grants
    • Lower maintenance costs
    • Energy efficiency
    • Customisation

    New homes are built to modern standards, which can mean better insulation, improved energy ratings, and fewer repair costs in the early years. The ability to design your home to suit your needs is also attractive to many first-home buyers.

    Challenges First Home Buyers Should Consider

    While building can be rewarding, there are risks that must be managed carefully. Construction projects can encounter delays or unexpected expenses, which may put financial pressure on the project.

    Potential challenges include:

    • Budget blowouts
    • Construction delays
    • Interest rate changes
    • Valuation risk

    Unexpected upgrades, material cost increases, or contract variations can increase total expenses. In addition, if the final property valuation is lower than expected, it may impact loan terms. Careful budgeting and contingency planning are essential before committing to a build.

    Step-by-Step Guide to Applying for a Construction Loan in Sydney

    Successfully applying for a construction loan requires preparation and organisation. Following a structured approach can speed up approvals and reduce stress.

    1. Save your deposit
    2. Review your credit file and reduce existing debts
    3. Obtain finance pre-approval
    4. Choose a land and a builder
    5. Sign a fixed price building contract
    6. Submit a full loan application
    7. Begin construction and manage progress payments
    8. Move in once construction is complete

    Each stage builds upon the previous one, so having clarity early can prevent complications later in the process.

    Tips to Improve Approval Chances

    First home buyers can strengthen their loan application by demonstrating financial stability and responsible money management. Lenders want confidence that repayments will be sustainable in the long term.

    Helpful strategies include:

    • Maintaining stable employment
    • Reducing credit card limits and personal loans
    • Avoiding large purchases before settlement
    • Demonstrating consistent savings habits
    • Working with a mortgage broker experienced in Sydney construction loans

    Seeking guidance from specialists such as Stryve Finance can help you navigate lender policy differences and present your application in the strongest possible way.

    Construction Loan vs Buying an Established Home

    Choosing between building and buying an established home depends on your financial situation, lifestyle goals, and risk tolerance. In Sydney, established homes in premium suburbs can command significant price premiums, while outer growth areas may offer more affordable land options.

    Building may offer advantages such as government incentives, lower initial maintenance costs, and modern design features. Buying an established home, on the other hand, allows immediate occupancy and greater certainty around timelines and neighbourhood character.

    Evaluating both options carefully will help determine which path aligns with your long-term financial objectives.

    Frequently Asked Questions

    Can I use the First Home Owner Grant for a construction loan

    Yes, eligible first home buyers can apply the grant toward construction costs, provided all criteria are met.

    How long does a construction loan approval take in Sydney

    Pre-approval can take several days to a few weeks. Formal approval after contract submission may take additional time, depending on lender requirements and the quality of the documentation.

    Do I pay rent while building?

    In most cases, yes. Many first home buyers continue renting during construction, so budgeting for dual housing costs is important.

    What happens if construction goes over budget

    You may need to cover additional expenses yourself unless the lender agrees to increase the loan amount, which is not guaranteed.

    Can I lock in my interest rate?

    Some lenders offer rate lock options for a defined period, though conditions and fees may apply.

    Conclusion

    First home buyers can absolutely obtain construction loans in Sydney. While the process involves more documentation and planning than purchasing an established home, it can provide significant advantages, particularly when government grants and modern building standards are considered.

    Preparation is critical. Understanding deposit requirements, lender expectations, and the staged funding structure will help you move forward with confidence. With the right guidance and careful budgeting, building your first home can be an achievable and rewarding pathway into the Sydney property market.

  • Co-Living Spaces: The Future of Urban Housing?

    Co-Living Spaces: The Future of Urban Housing?

    In 2025, co-living spaces are reshaping urban housing, offering affordable, community-driven alternatives for young professionals and digital nomads. As cities grow denser and housing costs soar, co-living has emerged as a solution that blends affordability, flexibility, and social connection. This article explores the rise of co-living spaces, their appeal to modern urban dwellers, and their profitability for property investors seeking high returns in a dynamic real estate market.

    What Are Co-Living Spaces?

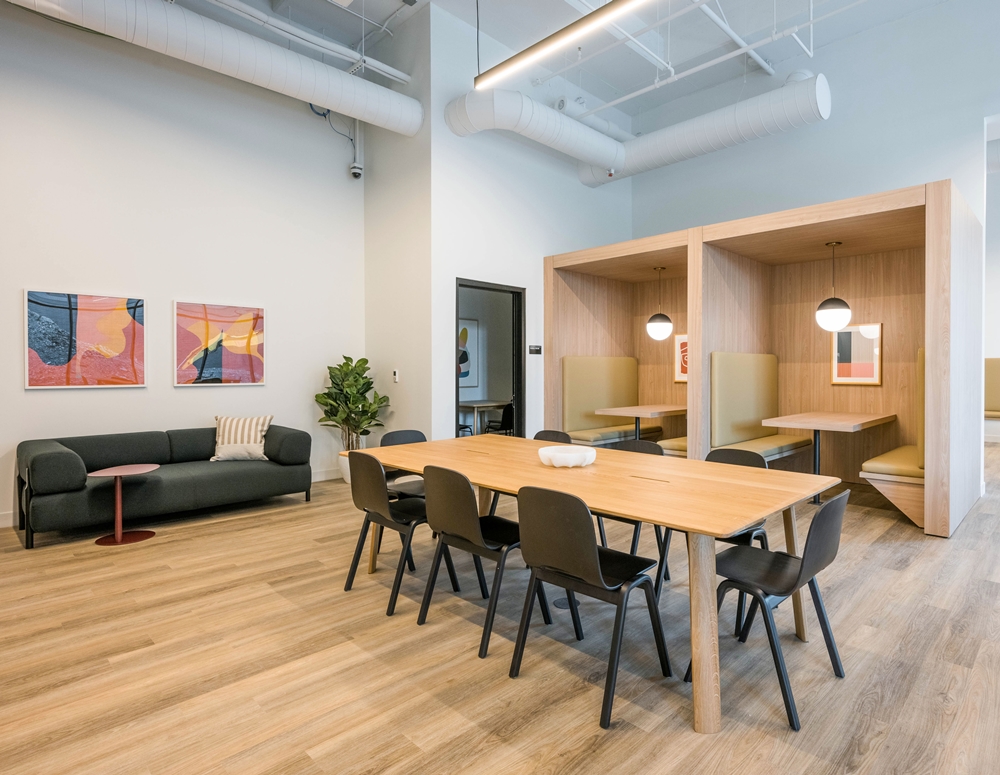
    Co-living spaces are shared living arrangements where residents rent private bedrooms but share common areas like kitchens, living rooms, and workspaces. Designed for convenience, these spaces often include utilities, Wi-Fi, cleaning services, and community events in the rent. Unlike traditional roommates, co-living emphasizes curated communities, attracting young professionals, freelancers, and digital nomads who value networking and flexibility over owning property.

    The concept has gained traction in cities like New York, London, and Singapore, where housing affordability is a challenge. For example, a 2024 report from CBRE noted a 15% increase in co-living developments globally, driven by demand from millennials and Gen Z. Co-living spaces cater to their need for short-term leases and vibrant, social environments, making them a cornerstone of modern urban housing.

    Why Co-Living Spaces Are Booming

    The rise of co-living spaces is tied to several trends. First, urbanization continues to drive young professionals to cities, where high rents and limited space make traditional apartments less viable. A Zillow study from 2024 found that median rent in major U.S. cities rose 7% year-over-year, pushing many toward shared living. Co-living offers an affordable alternative, with rents often 20-30% lower than studio apartments in the same area.

    Second, the digital nomad lifestyle is fueling demand. With remote work normalizing, many professionals seek flexible housing that supports their mobile careers. Co-living spaces offer short-term leases, sometimes as brief as a month, making them ideal for individuals who relocate frequently. Platforms like Outsite and Common report occupancy rates above 90% in key markets, reflecting strong demand.

    Finally, co-living fosters community, a key draw for younger generations. Residents often participate in organized events, from yoga classes to networking mixers, creating a sense of belonging. This social aspect differentiates co-living from traditional rentals, appealing to those who prioritize connection over isolation in bustling cities.

    Profitability for Property Investors

    For property investors, co-living spaces offer compelling financial opportunities. By converting traditional properties into co-living units, landlords can maximize rental income. For instance, a three-bedroom apartment that rents for $3,000 monthly could be reconfigured to house six co-living tenants at $800 each, generating $4,800—a 60% revenue increase. A 2024 Knight Frank report highlighted that co-living properties in urban markets yield 10-15% higher returns than traditional rentals.

    Investors also benefit from higher occupancy rates and diversified risk. Since co-living spaces attract multiple tenants per unit, the impact of a single vacancy is minimized. Operators like WeLive and The Collective report consistent demand, with waitlists in high-cost cities. Additionally, co-living’s all-inclusive pricing model (covering utilities and amenities) simplifies management and reduces turnover costs.

    However, challenges exist. Converting properties into co-living spaces requires upfront investment for renovations, such as adding bathrooms or soundproofing walls. Local regulations, like zoning laws or restrictions on short-term rentals, can also complicate operations. Investors must research markets carefully, targeting areas with high demand from young professionals, such as tech hubs or creative districts.

    The Future of Co-Living Spaces

    Looking ahead, co-living spaces are poised for growth as urban populations swell and housing preferences evolve. Innovations like smart home technology and sustainable design are enhancing their appeal. For example, some co-living operators integrate energy-efficient systems or co-working spaces to attract eco-conscious and remote-working tenants. A 2025 JLL forecast predicts co-living will account for 5% of urban rental markets by 2030, up from 2% today.

    Yet, challenges like regulatory hurdles and market saturation could slow expansion. Investors and operators must balance profitability with tenant satisfaction, ensuring spaces remain affordable yet desirable. Partnerships with developers to build purpose-built co-living properties could address these issues, offering scalable solutions for urban housing.

    Co-living spaces are more than a trend; they’re a response to the evolving needs of urban dwellers. For young professionals and digital nomads, they offer affordability, flexibility, and community. For property investors, they promise higher yields and stable demand. As cities adapt to new economic and social realities, co-living spaces may well define the future of urban housing, blending practicality with connection in an increasingly crowded world.

  • Brand Positioning Strategy: Stand Out in a Crowded Market

    Brand Positioning Strategy: Stand Out in a Crowded Market

    A well-defined brand positioning strategy is crucial to ensuring your business remains top-of-mind for customers and achieves impactful results. In marketing, brand positioning involves creating a unique space for your brand in the consumer’s mind, differentiating it from competitors. This blog will delve into the essentials of brand positioning, provide practical strategies, and explain how leveraging these techniques can elevate your business.

    What is Brand Positioning?

    Brand positioning is the strategic process of establishing a distinct image or identity for your brand in the minds of consumers. It’s more than just having a memorable logo or tagline. It’s about how your brand is perceived relative to competitors and how effectively you communicate its unique attributes.

    You must first identify what sets your product or service apart to create effective brand positioning. This involves understanding your unique selling propositions (USPs), whether it’s superior quality, exceptional customer service, or innovative features. Once identified, you can craft a positioning strategy that highlights these strengths and resonates with your target audience.

    Crafting Your Brand Positioning Strategy

    1. Identify Your Unique Value Proposition

    The cornerstone of a successful brand positioning strategy is a clear understanding of your brand’s unique value proposition (UVP). This is what differentiates your brand from competitors and provides a compelling reason for consumers to choose your product over others. Consider factors such as:

    • Product features or benefits that are unique
    • Exceptional customer service or experiences
    • Competitive pricing or value for money

    2. Understand Your Target Audience

    Effective brand positioning requires a deep understanding of your target audience. Research their preferences, pain points, and needs. This knowledge will help you tailor your messaging to resonate with them and address their specific concerns. Use tools like surveys, focus groups, and market research to gather insights into your audience’s behavior and preferences.

    3. Analyze Competitors

    Evaluate how competitors position themselves in the market. Identify their strengths and weaknesses, and pinpoint gaps that your brand can fill. Understanding the competitive landscape will help you craft a positioning strategy that differentiates your brand effectively and capitalizes on areas where competitors fall short.

    4. Develop a Compelling Brand Message

    Once you’ve identified your unique value proposition and understood your target audience, craft a brand message that communicates your UVP clearly and compellingly. Your message should convey what makes your brand unique, why it’s valuable, and how it meets the needs of your audience. Consistency in your messaging across all platforms is essential for reinforcing your brand’s position.

    Also Read: Safeguarding Your Business From Volatility And Uncertainty

    5. Implement and Monitor Your Strategy

    With your brand positioning strategy in place, it’s time to implement it across various channels—be it your website, social media, advertising campaigns, or product packaging. Consistency is key. Ensure that your brand’s message and visual identity align with your positioning strategy.

    Regularly monitor the effectiveness of your positioning efforts. Furthermore, use metrics such as customer feedback, market share, and sales performance to assess how well your strategy is working. Be prepared to adjust your approach based on performance data and evolving market conditions.

    person infornt of laptop

    Benefits of a Strong Brand Positioning Strategy

    A well-executed brand positioning strategy offers several benefits:

    • Enhanced Brand Recognition: A clear and distinct position helps your brand stand out and become more memorable to consumers.
    • Increased Customer Loyalty: When consumers understand what makes your brand unique and valuable, they are more likely to remain loyal.
    • Higher Sales and Revenue: Effective positioning attracts new customers and retains existing ones, driving sales and revenue growth.
    • Competitive Advantage: Strong positioning differentiates your brand from competitors, giving you an edge in the market.

    Conclusion

    A robust brand positioning strategy is vital for any business aiming to make a mark in the competitive market. By understanding your unique value proposition, targeting the right audience, and crafting a compelling message, you can create a brand that resonates with consumers and stands out from the competition.

    For businesses in Bali seeking expert guidance on developing and implementing a successful brand positioning strategy, consider collaborating with a branding agency in Bali. Their expertise can help you refine your approach, enhance your market presence, and achieve your business goals. Start shaping your brand’s future today and watch it thrive in the dynamic marketplace.

  • How Property Rentals Can Generate Revenue for Businesses

    How Property Rentals Can Generate Revenue for Businesses

    The sharing economy, a disruptive force in recent years, has transformed how people access resources and services. Businesses are no longer limited to traditional ownership models. The sharing economy opens doors to maximizing asset utilization and generating revenue through property rentals.

    Explores how businesses can leverage the sharing economy by renting out underutilized spaces and equipment, transforming fixed costs into valuable income streams.

    Unlocking Potential Through Shared Space:

    • Co-working spaces: Offices with flexible memberships and shared amenities offer businesses extra space and an opportunity to create co-working environments. These spaces cater to freelancers, remote workers, and startups seeking a professional workspace without long-term leases.
    • Event venues: Restaurants with banquet halls or bars with large patios can generate additional income by renting out their space for events after business hours. This caters to various occasions, from business meetings to private parties.
    • Storage solutions: Businesses with excess storage space can list it on online platforms catering to individuals or businesses seeking secure, affordable storage options.

    Read also, Buying Your 1st Investment Property: Mistakes to Avoid

    More Than Just Space: Sharing Equipment and Resources

    • Construction equipment: Construction companies often own specialized equipment used for short durations. Renting out this equipment during downtime can generate additional revenue and offset ownership costs.
    • Delivery vehicles: Businesses with fleets can rent out cars during off-peak hours to other companies or individuals requiring transportation solutions.
    • Manufacturing resources: Factories with underutilized machinery can offer their manufacturing capabilities to other businesses per project, maximizing production capacity and generating additional revenue.

    Embracing the Sharing Economy: Key Considerations

    • Identify underutilized assets: Businesses should conduct a thorough inventory to identify space, equipment, or resources that can be effectively shared without impacting their core operations.
    • Platform Selection: Choose a reputable sharing economy platform that caters to your specific type of asset and target audience. Consider factors like platform fees, reach, and user reviews.
    • Legal and insurance considerations: Ensure compliance with local regulations and obtain necessary insurance to protect your property and users while engaging in shared economy practices.
    • Customer service focus: Be clear, communicative & helpful to build sharing economy trust.

    The sharing economy offers a win-win situation for businesses and consumers. Companies, like those in the property rentals space, can maximize resource utilization by renting out unused space or assets. This can generate additional revenue streams and allow them to adapt to evolving market trends. By embracing the sharing economy, businesses can become more flexible and efficient and contribute to a sustainable economic model.

  • Things You Need To Do When Your Business Is Being Sued

    Things You Need To Do When Your Business Is Being Sued

    Among so many things that you think can happen to your happen, being sued might be the last one on your mind. However, it is possible to happen. For years, anyone in the business industry has known that lawsuits can happen for any reason. You can experience more legitimate scenarios where someone sues you. Knowing how to handle it is essential regardless of why you are being sued. 

    Handling business lawsuits properly

    Handle business lawsuits methodically to protect your business and prevent severe damage. Here are things you need to know about business lawsuits and how to handle them when you are on the receiving end of them:

    Understand the types of business lawsuits.

    You must defend yourself when sued, which can be taxing, draining, and time-consuming. Business lawsuits include breach of contract, intellectual property disputes, fraudulent behavior, slander accusations, partnership disputes, professional liability claims, and general liability claims. Learn more about those lawsuit types to educate yourself and make informed decisions.

    Confirm the name of the defendant.

    Confirm the defendant’s name if you are suing for any reason. Check if the lawsuit document lists the correct business entity. Ensure the company name is accurate, and check if you are also named personally.  

    Also read Buying Your 1st Investment Property: Mistakes to Avoid

    Gather all relevant records. 

    Collect all records, such as contracts, receipts, email correspondences, and other client information. Gather all the documents without assessing whether the data is pertinent to cost. Take them all to an attorney for review.  

    Get in touch with your attorney.

    If you already have an attorney working for you, make a phone call, review the details of the lawsuit together, and make a plan. If you don’t have an attorney ready, reach out to one. Hire an attorney who specializes in and has experience with your type of case. Find someone who can advise you properly and with dedication.

    Call your insurance provider.

    Your insurance provider may be able to handle some lawsuits, so make sure to call them to see what is covered and what isn’t. They will provide a legal defense for you and settle a claim or pay any judgment found. 

    Decide what action to take.

    You and your attorney may respond to a lawsuit after a discussion. You may admit what you are being accused of and pay the claim. It’s also possible to deny the claim or even counter-sue the plaintiff. Talk more about the pros and cons of each action with your attorney. 

     File a response

    You file a response to the claim with your attorney or insurance company. You need to include documentation that supports your side of the story. Remember that there is a deadline to file a response, so do it within the given timeframe. 

  • Buying Your 1st Investment Property: Mistakes to Avoid

    Buying Your 1st Investment Property: Mistakes to Avoid

    Investing in real estate can be an effective way to increase your strategy. Owning a rental property can offer passive income, long-term appreciation, and a valuable asset for your financial future. However, for first-time investors, the process can be daunting. Understanding and avoiding common mistakes is crucial for setting yourself up for success. Here, we explore some key pitfalls to avoid when venturing into the investment property world.

    Rushing into a Decision without a Plan

    Excitement about potential returns can lead to impulsive decisions. Stay away from the first property that catches your eye. Develop a clear strategy for investing before you start searching. Consider your financial goals, risk tolerance, and desired timeline.

    • Define Your Goals: Are you aiming for steady cash flow, capital appreciation, or a combination?
    • Assess Your Risk Tolerance: Investment properties have inherent risks, such as vacancies and repairs. Are you comfortable managing these potential challenges?
    • Set a Budget: When determining your budget, factor in the purchase price, closing costs, ongoing expenses, and potential vacancy periods.

    Read Also: Real Estate Around the World: A Global Perspective on Buying and Selling Property

    Ignoring Location, Location, Location

    Location remains paramount in real estate investment. A property’s value is significantly affected by its surroundings.

    • Research the Neighborhood: Look for areas with stable or rising property values, good rental demand, and low vacancy rates.
    • Consider Amenities: Proximity to schools, transportation, and desirable amenities can attract tenants and increase rental income.
    • Evaluate Long-term Growth Potential: Choose an area with potential for future development or job growth, which could increase property value.

    Focusing Solely on Purchase Price and Ignoring Underlying Costs

    While the purchase price is essential, there are other financial considerations. Factor in additional ongoing costs associated with owning an investment property.

    • Closing Costs: Be prepared for closing costs, including origination fees, title insurance, and property taxes.
    • Maintenance and Repairs: Budget for regular service and potential repairs. Unexpected breakdowns are a reality of property ownership.
    • Property Taxes and Insurance: Research annual property taxes and factor in homeowners’ or landlord’s insurance into your calculations.
    • Property Management Fees: When recruiting a real estate management company, consider their fees when determining your potential returns.

    Overlooking the Importance of Professional Inspections

    A thorough inspection by qualified professionals can uncover hidden issues that could significantly impact your investment. Take advantage of this crucial step.

    • Hire a Qualified Inspector: Get a home inspection to identify structural problems, necessary repairs, and the property’s overall condition.
    • Consider Additional Inspections: For older buildings, consider additional inspections like pest control, electrical systems, or plumbing.
    • Negotiate Repairs: Use the inspection report as leverage during negotiations with the seller to address any significant issues.

    Underestimating the Importance of a Strong Tenant

    A reliable and responsible tenant is essential for a smooth investment experience. A good tenant can lead to timely rent payments, property damage, and eviction headaches.

    • Develop a Screening Process: Implement a thorough tenant evaluation procedure that includes credit checks, job verification, and reference verification.
    • Set Clear Lease Agreements: A clear lease agreement outlining expectations, rent payment deadlines, and maintenance responsibilities is essential.
    • Maintain Positive Relationships: Build a positive relationship with your tenant to encourage long-term occupancy and minimize potential issues.
  • Real Estate Around the World: A Global Perspective on Buying and Selling Property

    Real Estate Around the World: A Global Perspective on Buying and Selling Property

    The global real estate market is a tapestry of diverse practices, laws, and property types. This expanded article delves deeper into the intricacies of buying and selling property in various countries, offering a richer understanding of the unique characteristics and challenges of each market.

    The United States: A Diverse and Dynamic Market

    In the United States, the real estate market offers a wide range of options, from high-rise apartments in New York to ranches in Texas. The National Association of Realtors reported that in 2022, the median U.S. home price was around $350,000, a figure that varies greatly by region. The process of buying a house involves several steps, including securing a mortgage, which about 87% of buyers do. Each state has its own set of laws, and property taxes can differ significantly.

    The United Kingdom: Navigating Complexity

    The UK real estate market is known for its historical properties and modern developments. The leasehold system, particularly prevalent in cities, involves owning a property for a set period, often up to 99 years, while freeholds represent outright ownership. According to UK government data, leasehold sales accounted for around 30% of all property sales in England and Wales in 2021. The process is known for its chain system, making transactions interdependent and sometimes causing delays.

    Japan: High-Tech and High-Density Living

    Japan’s real estate market is a reflection of its high-density living and technological advancements. With a focus on maximizing space, the average size of a new apartment in Tokyo is about 65 square meters. Earthquake resistance is a critical factor, with stringent building codes ensuring properties withstand seismic activity. Japan’s unique property valuation system, known as ‘chika-koji’, calculates land value based on location and use.

    Australia: Sun, Surf, and Sales by Auction

    Australia’s real estate market emphasizes properties that complement its coastal lifestyle. The Australian Bureau of Statistics noted that in 2022, over 70% of Australian households lived in standalone houses. The auction system is a distinctive feature. It sold around 30% of properties in major cities. Foreign investors are subject to restrictions and additional taxes, such as the Foreign Investment Review Board (FIRB) approval.

    A simple illustration showing a globe with iconic buildings from various countries

    India: A Rapidly Evolving Market

    India’s real estate sector is witnessing significant growth, with luxury developments increasingly common. The introduction of RERA in 2016 has brought more transparency and accountability. However, the process can be complex due to various bureaucratic layers and different regulations across states. In 2022, residential property sales in major cities increased by 30% compared to the previous year.

    Germany: A Renters’ Haven

    Germany’s property market is unique, with a strong preference for renting over buying. About 48% of the population lives in rented accommodation. The buying process is heavily regulated. It involves notaries, and tenant rights are among the strongest in the world, offering significant protection to renters.

    Conclusion

    Understanding the nuances of the global real estate market is essential for anyone looking to venture into international property investment. From the diverse property options in the U.S. to the unique auction system in Australia, each country presents distinct opportunities and challenges. This exploration underscores the importance of local knowledge and expertise when navigating the complex landscape of global real estate.